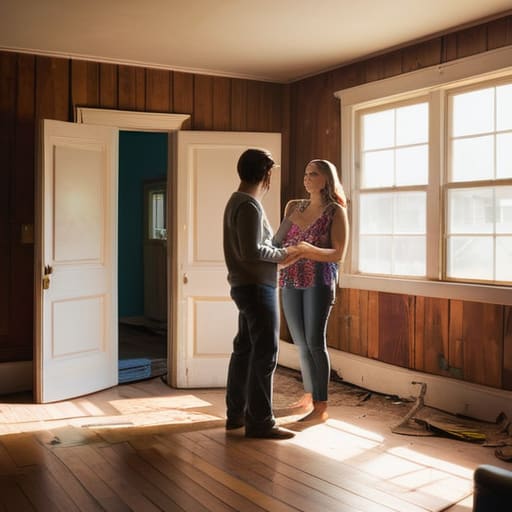
I still remember standing in the middle of my first “investment” property—a damp, drafty bungalow that smelled faintly of mildew and regret—clutching a generic, thirty-page PDF I’d downloaded online. That useless document was filled with fluff about credit scores and escrow periods, but it told me absolutely nothing about how to spot a cracked foundation or a wiring nightmare behind a fresh coat of beige paint. Most people will hand you a standard first time home buyer checklist that treats house hunting like a math equation, but they forget that you’re actually buying a physical structure that can either build your wealth or drain your bank account.
I’m not here to give you a lecture on mortgage interest rates that you could find on any banking blog. Instead, I’m giving you the gritty, boots-on-the-ground reality of what you actually need to look for when you’re standing in a living room that looks “perfect” but feels wrong. My goal is to hand you a tactical first time home buyer checklist designed to help you separate the structural disasters from the diamond-in-the-rough opportunities. We’re going to focus on finding the potential that others miss, so you can start turning crumbling walls into solid equity.
Mastering the Mortgage Pre Approval Process and Credit Score Requirements
Before you even step foot in a dusty fixer-upper, you need to know exactly what you can afford. I’ve seen too many people fall in love with a property only to realize their math was off. Don’t just guess your numbers; use a home buying budget planner to account for the hidden stuff, like those inevitable repair surprises. Once you have a realistic grasp on your finances, you need to tackle the heavy lifting: the mortgage pre-approval process. This isn’t just a formality; it’s your golden ticket. It proves to sellers that you aren’t just a dreamer, but a serious buyer with the backing to close the deal.
While you’re at it, take a hard look at your credit. Understanding the specific credit score requirements for mortgage lenders is non-negotiable if you want the best interest rates. A higher score isn’t just a vanity metric; it’s the difference between a manageable monthly payment and a financial sinkhole. I treat my credit score like a renovation budget—if you don’t manage it carefully from the start, you’ll end up paying for it in the long run.
Building Your Home Buying Budget Planner for Maximum Potential
Once you’ve cleared the hurdle of the mortgage pre-approval process, it’s time to get real about the numbers. Most people make the mistake of thinking their budget is just the monthly mortgage payment, but if you’re hunting for fixer-uppers, that mindset will bankrupt you. You need a robust home buying budget planner that accounts for more than just the sticker price. I always tell my clients to carve out a specific “renovation contingency” fund. If you find a house with incredible bones but a dated kitchen, you need to know exactly how much liquid cash you have to turn that dated space into instant equity.
Don’t forget the hidden drains on your bank account. You need to factor in closing costs explained in your initial math—things like title insurance, legal fees, and transfer taxes can easily eat up several percentage points of the purchase price. If you’re looking for a property with high potential, you can’t afford to be caught short when the final settlement papers hit the table. Plan for the unexpected so a minor plumbing surprise doesn’t derail your entire investment strategy.
Beyond the Bank Account: 5 Real-World Filters for Your Property Hunt
- Look past the “ugly” to find the bones. I don’t care if the wallpaper is a hideous 70s floral or the carpet is stained; I’m looking at the layout, the ceiling height, and the integrity of the foundation. If the structure is solid, the aesthetics are just a math problem I can solve with a sledgehammer and some sweat equity.
- Scout the neighborhood’s trajectory, not just the street. A house might be a steal, but if the surrounding area is stagnant, your equity won’t grow. I always check local zoning plans and upcoming infrastructure projects—you want to buy where the city is heading, not where it’s been.
- Factor in the “hidden” renovation tax. When you’re calculating your budget, don’t just look at the mortgage. You need a contingency fund—at least 15% of your total project cost—for the inevitable surprises like outdated wiring or a subfloor that’s seen better days. If you don’t budget for the mess, the mess will eat your profit.
- Get a professional inspector who isn’t afraid to get dirty. Don’t rely on a quick walkthrough or a pretty staging job. You need someone to crawl into the attic and check the crawlspace. I’ve walked away from “perfect” looking houses because the inspector found a foundation issue that would have turned my dream flip into a financial nightmare.
- Prioritize “High-ROI” upgrades in your checklist. If you’re planning to renovate, don’t waste money on high-end custom built-ins that only you will love. Focus on the things that drive appraisal value: updated kitchens, clean bathrooms, and curb appeal. You’re building an asset, not just a personal sanctuary.
From Paperwork to Property
Look, I know the sheer volume of this checklist feels overwhelming. Between securing that pre-approval, obsessing over your credit score, and mapping out a budget that actually accounts for the inevitable “oops” moments during a renovation, it’s easy to feel like you’re drowning in spreadsheets. But remember: every single one of these steps is designed to protect you. By mastering your financing and building a realistic budget now, you aren’t just buying a house; you are structuring a foundation for a real asset. Don’t skip the boring parts, because the devil is always in the details when it comes to protecting your equity.
At the end of the day, a house is more than just four walls and a roof—it is the first physical brick in the wall of your financial future. You might be looking at a property with peeling paint and outdated flooring right now, but I see a canvas. Don’t let the fear of a messy process stop you from seizing an opportunity. If you have the patience to do the homework and the grit to handle the chaos, you can turn a fixer-upper into a legacy-building powerhouse. Now, grab your keys, stop overthinking, and go find your diamond in the rough.
Once you’ve got your budget locked in, you need to start looking at the actual bones of a property, and that’s where things get real. I always tell my clients that a pretty kitchen can hide a foundation nightmare, so you have to be methodical about your walkthroughs. If you’re feeling a bit overwhelmed by the logistics of scouting new locations or managing the finer details of your search, I’ve found that using a resource like ao huren can help streamline the process. It’s all about having the right tools in your belt so you can focus on spotting the true potential in a space rather than getting bogged down in the administrative weeds.
